


Borrow Money: Fast Cash Loan
4.71.07K Reviews
App Specs
- Version
- 0.2.2
- Updated On
- License
- Free
- Downloads
- 100,000+
- Developer
- Dollar Loan Center
- Categories
- Finance
- Platform
- Android
Screenshots
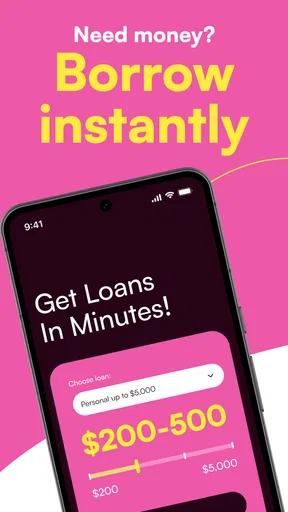
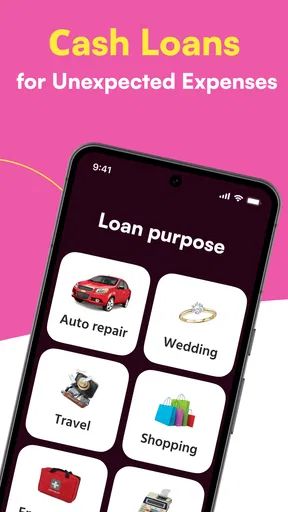
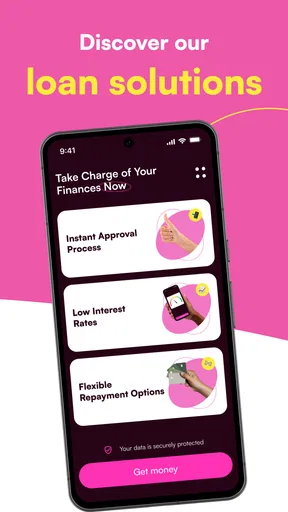
 Analysis by AppCompare
When an unexpected bill lands between paydays, the difficult part is often not deciding that you need help; it is finding an option that is quick enough, clear enough, and realistic for your financial situation. I tested Borrow Money: Fast Cash Loan with that exact pressure in mind. It is a free finance app from Dollar Loan Center, built around requesting a cash advance rather than managing a full banking relationship. The focus is immediate borrowing, including situations where a traditional lender may be less welcoming to people with poor credit.
My first impression was that this is a focused tool, not an all-purpose money manager. You will not open it expecting budgeting dashboards, investment tracking, or a replacement for your bank. Its value is narrower: it gives you a mobile starting point for exploring a short-term loan. That narrow purpose can be useful when time matters, but it also means the quality of your experience depends heavily on the information you enter and the terms you receive during the application process.
Who this app makes sense for
I would consider this app when a person has a specific, urgent expense and already has a credible plan for repayment. A utility bill, a necessary repair, or a gap before the next paycheck are very different from borrowing for an open-ended shopping spree. The app may also be worth considering for someone whose credit history makes ordinary personal-loan applications difficult, since its store summary specifically presents access for people with bad credit.
That does not make borrowing automatically affordable. A convenient application can make a loan feel less serious than it is. Before entering anything, I would write down the amount needed, the date money should arrive, and the exact source of repayment. If those three points are unclear, I would pause rather than treat the app as a solution to a continuing shortage.
The app is less suitable for consolidating several debts, planning long-term finances, or comparing a wide range of lenders in one place. Someone with good credit and time to shop around may get better value from a bank, credit union, or established loan-comparison service. Those alternatives can take longer, but patience may bring a lower overall cost. This app is most relevant when speed and access matter more than a broad comparison experience.
Beginning with the real problem, not the loan amount
The strongest way to use Borrow Money: Fast Cash Loan is to begin outside the app. I would first calculate the unavoidable expense and remove anything optional. If a bill can be delayed without a penalty, or if a provider offers a payment arrangement, that may be safer than borrowing. The app should be the next step after those possibilities have been considered, not the first response to every uncomfortable balance.
Once I know the required amount, I would prepare basic personal and financial information before opening the application. This reduces the temptation to guess simply because I want to finish quickly. It also makes it easier to notice when an offer does not fit my budget. A useful rule is to judge the repayment amount against the money left after rent, food, transport, utilities, and existing obligations—not against gross income or the current account balance.
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
The app is free to install, but that should not be confused with free borrowing. The important financial questions concern the loan offer itself: how much must be repaid, when repayment is due, and whether any associated charges apply. I would read those details carefully before accepting anything. A free download is only an entry point; it says nothing by itself about the cost of accessing cash.
Moving through the application
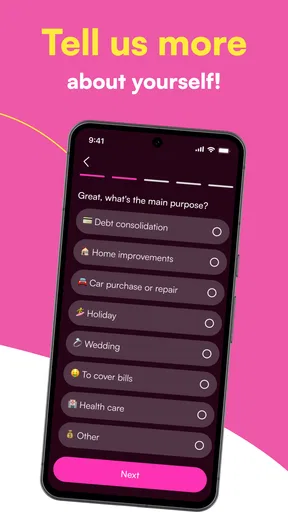
The basic workflow is straightforward in concept. I would open the app, provide the requested details, review the result, and decide whether to continue. The useful part is that this process can begin from a phone instead of requiring a visit to a branch. For a person dealing with a time-sensitive expense, that convenience may be the main reason to try it.
Still, “fast” should be read as a description of the intended experience, not a promise that every applicant will receive money immediately. An application can involve identity checks, eligibility decisions, additional questions, or a waiting period before funds are available. My practical advice is not to schedule a payment around expected money until the application has actually reached the point where the funds and repayment terms are clear.
Accuracy matters at every screen. A misspelled address, outdated employment detail, or incorrect bank information can create avoidable friction. I would slow down for fields that affect identity or repayment, even if the rest of the process feels quick. Saving a screenshot or note of the final offer is also sensible, because it gives you a personal record of what you accepted and when the repayment obligation begins.
One less obvious trade-off is the difference between eligibility and affordability. An application may lead to an offer even when the repayment schedule would strain your budget. I would treat approval as permission to consider the offer, not as evidence that taking it is wise. The final decision should come from the numbers in my own budget, not from the emotional relief of seeing a possible solution.
The handoffs that deserve attention
A cash-advance app is not the entire transaction. There are handoffs between you, the app, the developer’s lending operation, identity or eligibility checks, and the account used for receiving or repaying funds. Each handoff is a point where timing or information can become important. If a transfer is delayed, the original bill does not automatically move with it.
I would therefore keep the original creditor or service provider in the loop when appropriate. If the money is intended for a bill, confirm whether the payment deadline can be extended while the loan application is processed. This simple step can prevent a late fee if the expected transfer takes longer than hoped. It also avoids borrowing more than necessary just because the first deadline feels immovable.
Privacy is another part of the handoff. A finance application may require sensitive personal information to evaluate an application, so I would review every permission and disclosure presented during use rather than tapping through automatically. I would also install the app only through the official Android or iOS store associated with my device and check that the developer name shown is Dollar Loan Center. That small verification step helps avoid confusing the legitimate product with an unrelated copy.
If you share a device with someone else, I would be especially careful about notifications, saved credentials, and visible application details. Borrowing information is personal. A quick application is not worth exposing account or identity details to another person who can access the phone.
A realistic payday-gap scenario
Imagine that my car develops a problem two days before payday and the repair is necessary for getting to work. I would first ask the repair shop whether a partial payment or short extension is possible. If that fails, I would calculate the smallest amount that covers the repair, open Borrow Money: Fast Cash Loan, and complete the application with current information.
At the offer stage, I would compare the repayment obligation with the money available after my regular payday expenses. If repaying the advance would leave me unable to cover rent or groceries, I would reject it even if the application was approved. If the amount fits, I would record the due date, keep the confirmation, and avoid taking another advance to cover unrelated spending. The app can help bridge a narrow gap; it should not become the mechanism for creating the next gap.
After receiving funds, I would still check that the repair payment and transfer were completed as expected. The outcome is not finished when the application says approved. It is finished when the urgent expense is handled and the repayment plan is understood. That distinction is important because digital convenience can make the middle of the process feel like the end.
What the result feels like in practice
The app’s main strength is concentration. It is designed around borrowing, so a user who already knows the purpose of the application is not forced to navigate unrelated financial tools. The mobile format can also be more practical than a branch visit for someone working irregular hours or dealing with an immediate expense.
Its public reception is encouraging: it carries a 4.7 average from around 21 thousand ratings, with roughly 1.1 thousand written reviews. I see that as evidence that many users find the experience useful, but not as a guarantee that every applicant will receive the same result. Loan eligibility, timing, and affordability are personal, and a high rating cannot replace reading an individual offer.
The app has passed 100 thousand installs, which gives it a meaningful user base for a relatively recent product. It was released on August 6, 2024, and the current version is 0.2.2. Those details suggest a product that is still comparatively early in its lifecycle. I would keep the app updated and pay attention to changes in the application flow, especially if I return to it later for another financial decision.
It is rated for Everyone and runs on Android 7.0 or later, so device compatibility should be broad for people using older Android phones. That does not remove the need to protect the device itself. A screen lock, current operating-system security, and careful handling of notifications are just as important as the app’s borrowing workflow.
Where the workflow can break down
The first failure point is overestimating speed. A person may download the app because a bill is due today, only to discover that the application still needs review or that the transfer does not arrive on the expected schedule. I would never rely on a pending application as the sole plan for a deadline. A backup arrangement with the biller is more responsible than assuming the app can control every timing step.
The second is accepting an amount that is larger than the real need. A higher offer can look reassuring, but extra borrowed money also creates extra repayment pressure. I would request or accept only what directly solves the urgent expense. If the app presents an amount that does not match the budget, that is a reason to stop, not a reason to spend the difference.
The third is misunderstanding the total obligation. Short-term borrowing can be costly when viewed over the full repayment period, even if the initial amount appears manageable. Before accepting, I would look for the total repayment, due dates, any fees, and what happens if payment is late. If those details are not easy to understand, I would not proceed until they are clear.
There is also a practical limitation for people who need ongoing financial support. The app may help with one defined emergency, but repeated borrowing can turn a temporary bridge into a cycle. If I needed advances regularly, I would stop using the app as a recurring fix and seek help from a nonprofit credit counselor, a trusted financial adviser, or the companies receiving my bills. A different option is better when the underlying problem is monthly cash flow rather than one isolated expense.
How it compares with familiar alternatives
Compared with a bank or credit union, Borrow Money: Fast Cash Loan is more appealing when a person values a mobile-first starting point and may not fit conventional credit expectations. A bank relationship may offer more established account tools and potentially more favorable borrowing for qualified customers, but it can involve stricter requirements or a slower process. The right choice depends on whether access, cost, or speed is the priority.
Compared with a credit card, the app may feel more structured because the borrowing is tied to a specific application and repayment obligation. A credit card can be useful for someone who already has available credit and can repay quickly, but it can also encourage ongoing balances. I would compare the full cost and repayment timing rather than assuming either option is automatically cheaper.
Compared with asking a bill provider for an extension, borrowing adds a new financial obligation. An extension or payment arrangement may be inconvenient, but it may cost less than taking a cash advance. I would make that call before applying whenever possible. The app is most defensible when the expense is genuinely urgent, the provider cannot offer flexibility, and the repayment plan is solid.
Compared with informal help from family or friends, the app offers a more formal route but may be less flexible emotionally and financially. A personal loan from someone close can create relationship tension, while a formal product creates contractual obligations. Neither route should be chosen casually; I would focus on clarity, repayment ability, and privacy in either case.
My practical checklist before tapping accept
I would use the following sequence every time, even if the application feels simple:
- Write down the exact emergency expense and remove optional spending from the calculation.
- Ask the biller, employer, or service provider whether a short extension or payment arrangement is available.
- Enter current personal and financial details, checking spelling and account information carefully.
- Review the total repayment, due date, fees, and late-payment consequences rather than focusing only on the amount offered.
- Confirm that repayment still works after essential expenses, not merely after the next paycheck arrives.
- Save the final confirmation and monitor both the receiving account and the original bill.
- Do not apply for another advance to cover the first one unless a qualified professional has helped assess the situation.
This checklist adds a little time, but it protects the main benefit of the app: speed without completely surrendering judgment. The fastest application is not the best outcome if it creates a larger problem a few weeks later.
My conclusion after following the full journey
Borrow Money: Fast Cash Loan is a focused option for people who need to investigate a short-term cash advance from a phone, particularly when poor credit makes ordinary lending routes difficult. I like its direct purpose, free access, broad Android compatibility, and the fact that its strong rating indicates a positive experience for many users. Dollar Loan Center has made the first step convenient for a specific kind of financial emergency.
My recommendation is conditional rather than automatic. Use it only for a defined need, verify every repayment detail, and keep a backup plan for the bill while the application is still pending. If you have time to compare offers, a credit union or bank may be better. If the expense can be negotiated, an extension may be safer. If borrowing has become a monthly habit, this app is not the real solution.
For the right situation, the workflow can be useful: identify the gap, apply carefully, inspect the handoffs, confirm the money arrived, and repay according to the terms. For the wrong situation, the same convenience can hide the seriousness of the commitment. I would recommend it to a disciplined user facing one urgent, manageable expense—not to someone looking for unlimited spending room or a substitute for a sustainable budget.
Pros
- Quick application process with minimal paperwork
- Clear repayment schedule shown before accepting the loan
- Useful for handling short-term
- unexpected expenses
- Mobile-friendly design makes account access convenient
- Loan status and payment details are easy to track
Cons
- Interest and fees may make borrowing expensive
- Approval and loan terms can vary by applicant
- Late payments may lead to extra charges or penalties
- Not suitable for long-term financial needs
- Availability may depend on your location and eligibility
FAQs for Borrow Money: Fast Cash Loan
What is Borrow Money: Fast Cash Loan, and how does it work?
Borrow Money: Fast Cash Loan is a financial app designed to help users explore short-term borrowing options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess eligibility. Available loan amounts, approval decisions, interest rates, fees, and repayment terms can vary by applicant and location.
Is Borrow Money: Fast Cash Loan a direct lender?
Before applying, it is important to understand the app’s role in the borrowing process. Some loan applications act as lending marketplaces or connection services rather than providing money directly. In that case, your information may be shared with participating lenders, and the final offer comes from a third party. Carefully review the provider’s disclosures, lender identity, annual percentage rate, fees, and terms before accepting anything.
What information does the app require, and is it safe to provide?
The application may request details such as your name, address, date of birth, employment status, income, bank account information, and identification data. Because this is sensitive financial information, download the app only from an official store and review its privacy policy carefully. Check what data is collected, why it is used, whether it is shared, and how you can request account or data deletion.
How much does borrowing through the app cost?
The total cost depends on the lender and the offer you receive, not simply on the amount borrowed. Review the annual percentage rate, interest, origination or administration fees, late-payment charges, repayment schedule, and any automatic-debit conditions. A fast approval does not necessarily mean an affordable loan. Compare the complete repayment amount with alternatives before agreeing, especially if the term is short.
What should I do if I cannot repay the loan on time?
Contact the lender as soon as you realize repayment may be difficult. Ask whether an extension, revised payment arrangement, or hardship option is available, and request all changes in writing. Missing payments can result in additional fees, collection activity, or damage to your credit history, depending on the provider and local regulations. Never pay an upfront fee to a person claiming they can guarantee approval or erase debt.


